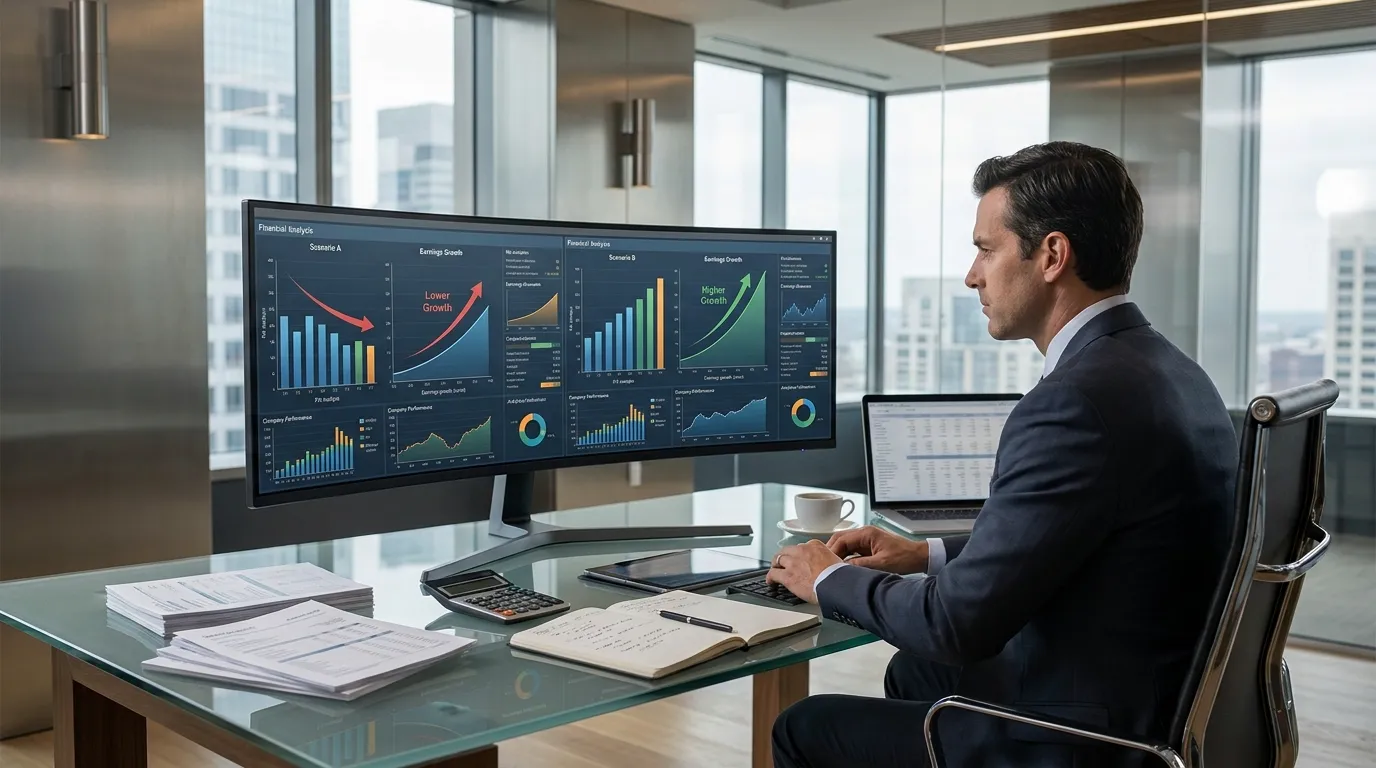
A P/E ratio shows what investors are paying for a company’s earnings. A PEG ratio helps assess whether the company’s expected growth justifies that price.
One of the most common ways of evaluating a listed company is through its Price-to-Earnings, or P/E, ratio. Investors often assume that a company with a low P/E is reasonably valued, while one with a high P/E is expensive. Although the ratio is useful, this conclusion can be misleading when the company’s future growth is not considered.
The P/E ratio is calculated by dividing the market price per share by the company’s earnings per share.
P/E Ratio = Market Price per Share ÷ Earnings per Share
If a company’s share price is ₹200 and its earnings per share are ₹10, its P/E ratio will be:
₹200 ÷ ₹10 = 20
This means investors are paying ₹20 for every ₹1 earned by the company. However, the calculation only explains the relationship between the share price and earnings. It does not tell us how quickly those earnings are expected to grow.
This is where the Price/Earnings-to-Growth, or PEG, ratio can provide additional context.
PEG Ratio = P/E Ratio ÷ Expected Earnings Growth Rate
Consider two companies operating under similar market conditions. Company A trades at a P/E of 20 and is expected to grow its earnings by 10% annually. Its PEG ratio would be:
20 ÷ 10 = 2
Company B trades at a higher P/E of 35 but is expected to grow its earnings by 30% annually. Its PEG ratio would be:
35 ÷ 30 = 1.17
Company A appears less expensive if we compare only the P/E ratios. Once expected growth is considered, however, Company B may be more reasonably valued. Investors are paying a higher multiple, but they are also expecting significantly higher earnings growth.
This does not mean that the company with the lower PEG ratio is automatically the better investment. The growth rate used in the calculation is generally an estimate, and any change in that estimate can materially affect the result.
For example, suppose a company trades at a P/E of 30 and is expected to grow its earnings by 30%. Its PEG ratio is 1.
30 ÷ 30 = 1
If the company eventually grows by only 15%, the calculation becomes:
30 ÷ 15 = 2
The share price and the original P/E may remain the same, but the valuation now appears much more demanding because the expected growth has not been delivered.
This is why the quality of growth must be studied along with the rate of growth. Earnings supported by stronger sales, pricing power, market-share gains and healthy cash flows are more dependable than earnings created through excessive borrowing, repeated dilution or one-time gains. A business growing at a moderate but sustainable rate can be more valuable than one reporting rapid growth that requires continuous external capital.
The P/E ratio can also be misleading in cyclical industries. A company may report unusually high earnings during a favourable cycle, which makes its P/E look low.
Suppose a company’s share price is ₹300 and its current earnings per share are ₹30. Its P/E ratio is 10.
₹300 ÷ ₹30 = 10
If ₹30 represents peak-cycle earnings and the company normally earns ₹15 per share, its normalised P/E would be:
₹300 ÷ ₹15 = 20
The company was not necessarily inexpensive. Its temporarily high earnings made it appear so. Investors evaluating cyclical businesses must therefore consider normalised earnings rather than depending only on the latest financial year.
In my experience, P/E and PEG are both useful as starting points, but neither should be treated as a complete valuation method. They must be considered with cash-flow generation, return on capital, debt, management quality, governance, competitive position and the sustainability of future earnings.
For promoters, family offices and long-term investors, the decision also needs to fit within the wider portfolio. Even a fundamentally strong company may not be suitable if it increases exposure to a sector, economic cycle or risk that is already heavily represented in the family’s business and investments.
P/E tells us how much we are paying for a company’s earnings. PEG helps us compare that price with the expected rate of growth. The final investment decision, however, depends on whether that growth is realistic, sustainable and available at a valuation that provides sufficient room for uncertainty.
A low P/E is not always a sign of value, just as a high P/E is not always a sign of overvaluation. The numbers become meaningful only when they are considered in the context of the business behind them.
Disclaimer: The views expressed are for educational purposes only and should not be considered investment advice or a recommendation to buy or sell any security.